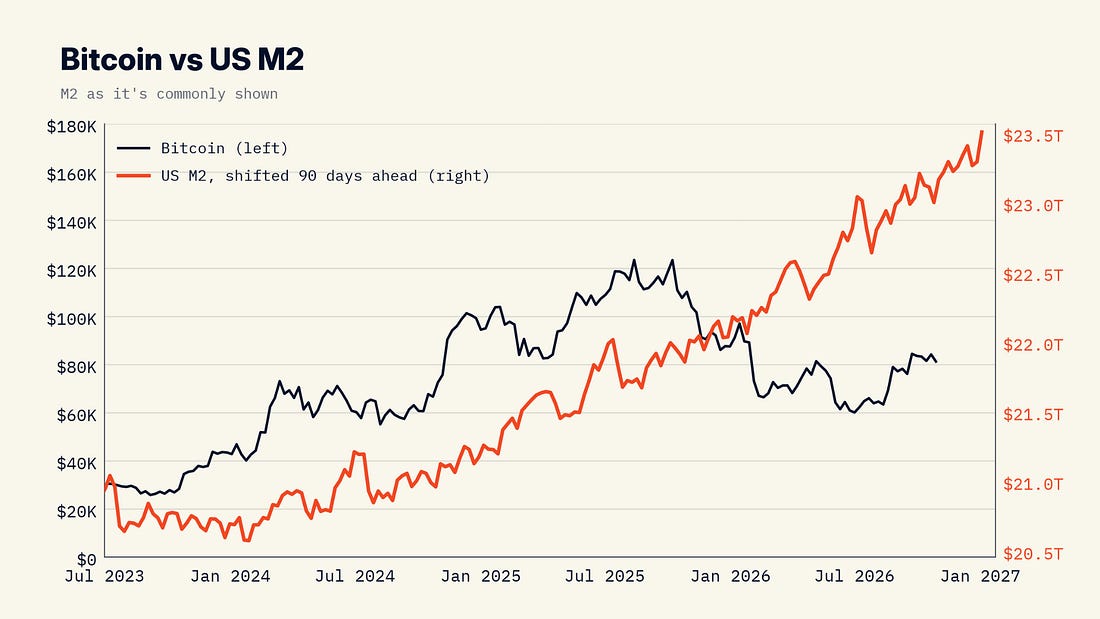
“Analyst Angle” October 2026 Sean Hagan, MBA I recently tested the theory every Bitcoiner has seen plastered across their timeline. That is that the price of Bitcoin follows M2, and when the M2 chart goes up and to the right we need only wait for the catch up HODLers are owed. With how wide the gap between the two has become, that relationship would deliver incredible returns and, as a Bitcoiner, I would be quite happy. Unfortunately, this theory does not survive a closer look. An alternative measure, net liquidity, proved to be a better measure of what the M2 crowd is after in that it tracks Bitcoin most closely in certain conditions. Even so, this better measure doesn’t lead Bitcoin’s price. Below are my findings.
1. The Claim The M2 argument rests on an intuition I share. When more dollars are chasing a fixed supply of scarce assets, some of those dollars should end up bidding on the scarce assets, and no assets are as scarce as Bitcoin. You’ve all seen the visuals on your timeline. An M2 chart is laid over a Bitcoin chart, fit so that the two rhyme. At worst the gap is read as a debt the market owes HODLers, and at best it’s viewed as a leading directional indicator. 2. Sufficient Evidence Before beginning the evaluation I’d like to square away what findings would serve as sufficient evidence towards the proposed relationship holding. The popular view implies four conditions, which I have listed in rough order of necessity.
It’s also important to apply a practical standard across the tests. These five rules govern every test applied in my following examination.
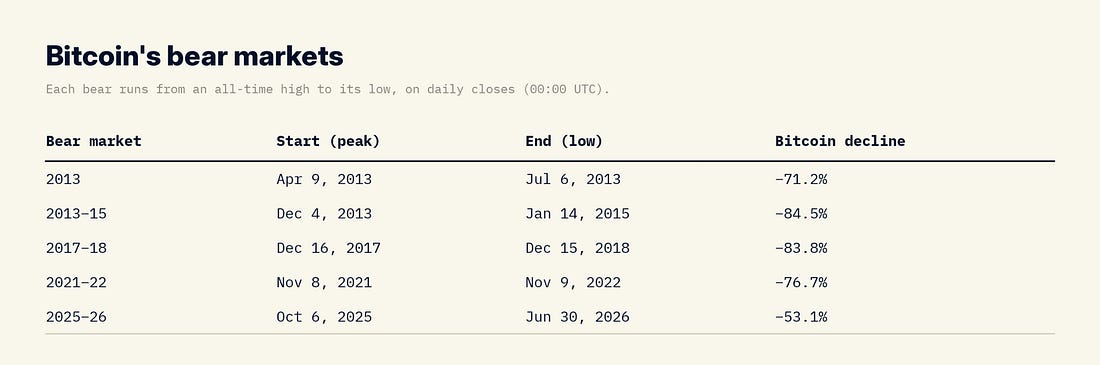
For M2 I used the weekly series (WM2NS), lagged for its publication delay, so my M2 verdict covers the US series specifically. 3. Why Net Liquidity Is the Better Measure of the Same Idea My disagreement with the M2 crowd is about the instrument rather than the intuition. If the idea is that a portion of newly available money spills into risk, then the measure we watch should track money that is actually free to spill, and M2 does a poor job of that. M2 is a stock. It counts every checking balance, savings deposit, small time deposit and retail money fund share in the country at a point in time, and almost all of it is already spoken for. Most of it is payroll waiting to be paid, rent waiting to be sent, or savings that have sat in the same account for years. The stock also grows for reasons that have little to do with anyone’s appetite for investment or speculation, because a larger population, rising wages, higher prices and ordinary bank lending all add to it. So when M2 rises, most of what we are watching is the economy getting bigger in nominal terms. Bitcoin’s price is set at the margin by whoever is buying or selling this week, so while it should respond to the flow of money that is free to move, a slowly growing stock says very little about that flow. The money that actually settles trades between the institutions that make markets is reserves, the balances that banks hold at the Federal Reserve. Deposits sit on top of reserves, and the two can drift apart for long stretches. When the Fed buys bonds it creates reserves, and the deposits of whoever sold the bonds rise at the same time. When the Fed lets bonds roll off, the reverse happens. Net liquidity is the Fed’s total assets minus the Treasury General Account minus the overnight reverse repo facility, since cash the Treasury parks at the Fed or money funds lend it overnight isn’t working in markets. It reads the reserve side directly, while M2 picks up the deposit side late and blends it with everything else that moves deposits. Timing matters too. M2 changes slowly, and it reaches us weeks after the fact. The pieces of net liquidity are published every week and can swing hard within a single quarter when the Treasury rebuilds its cash or when money funds move in or out of the reverse repo facility. If liquidity really does lead Bitcoin, a measure that serves as a more sensitive, immediate, and relevant barometer of the market should be the instrument of choice. For these reasons I think of net liquidity as the better arrow for what the M2 crowd is aiming for. It is narrower than M2, it sits closer to the mechanism they describe, and it moves more quickly. It also has a rather simple property that matters for an honest test. Net liquidity can fall, and it has fallen for long stretches, so any fit it shows with Bitcoin can’t be manufactured by two lines that both happen to rise. If the liquidity idea holds anywhere, it should hold here, and if it fails here, better data on the money stock is unlikely to rescue the M2 version. 4. How I Divided the Record Every test below runs on the same data for both measures. The main sample is 166 monthly readings from January 2013 through October 2026, each taken on the last Wednesday of the month and paired with Bitcoin’s close two days later. M2 is shifted about four weeks for its publication delay and uses today’s revised values, and in Section 6 I check what happens when both measures get the same timing. I measure changes over one, three and twelve months, since the lead most often claimed for the overlay is about a quarter. The backdrop test is an exception. It uses weekly data and sorts each week by how much liquidity changed over the prior 13 weeks, which is simply a quarter counted in weeks, because that is the reading behind the headline chart. A pooled number over fourteen years can hide very different behavior inside it, so I also split the record three ways. The first split is bull and bear markets, dated from Bitcoin’s daily closing price alone. A bear market starts at an all time high that is later followed by a decline of at least 50%, and it ends at the low. Everything between bears is a bull market. That rule finds six declines, and I count five of them as bears for the reason given below the table.
That leaves 117 bull months and 49 bear months. The bull that began on June 30, 2026 is provisional, since nobody knows yet where it peaks. I’d like to note that I treat the 53.1% retracement between April and July of 2021 as a correction inside the bull, in line with most analysts’ consensus. I did however rerun the bear tests counting 2021 as a bear, and I note below where that changes anything. The second split is the Fed’s rate policy. I call a month a hiking month when the upper end of the fed funds target is higher than it was six months earlier, a cutting month when it is lower, and on hold otherwise. By that rule the Fed was hiking from December 2015 to May 2016, from December 2016 to May 2019, from March 2022 to December 2023, and again since September 2026, after it raised the upper target to 4% at its September 16 meeting (effective September 17). It was cutting from August 2019 to August 2020, from September 2024 to May 2025, and from September 2025 to May 2026. That gives 60 hiking months, 31 cutting months and 75 months on hold. The third split is the Fed’s balance sheet, because rate policy and balance sheet policy have not always pointed the same way. I call the balance sheet growing when total assets rose more than 1% over the prior six months, shrinking when they fell more than 1%, and flat otherwise. It was growing from January 2013 to February 2015, from October 2019 to June 2022, and from April to September 2026. It was shrinking from January 2018 to September 2019 and from September 2022 to November 2025. That gives 65 growing months, 60 shrinking months and 41 flat months. Because the rule looks back six months, it lags announced policy. Runoff began in October 2017 and June 2022, but the rule first reads shrinking in January 2018 and September 2022. For every correlation I report how often chance does as well. I slide Bitcoin’s history forward by every offset of at least a year, wrap the end around to the start, and recompute the same statistic each time. The share of those shifted versions that match or beat the real result is the number in parentheses in the tables, and I treat anything under 5% as clearing chance. Splitting the record this many ways creates its own problem. Each measure has 32 split results, and they overlap, since the same months sit in several groups and the horizons share months. So I also run the shifting on all 32 at once. Under chance an average of about 1.6 of them fall under 5%, and in about one shifted history in twelve to sixteen, six or more do. I keep that in mind when a single cell looks good. 5. US M2 Examined
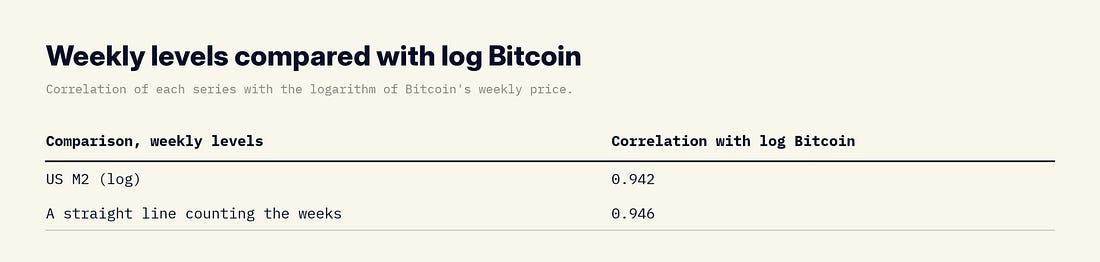
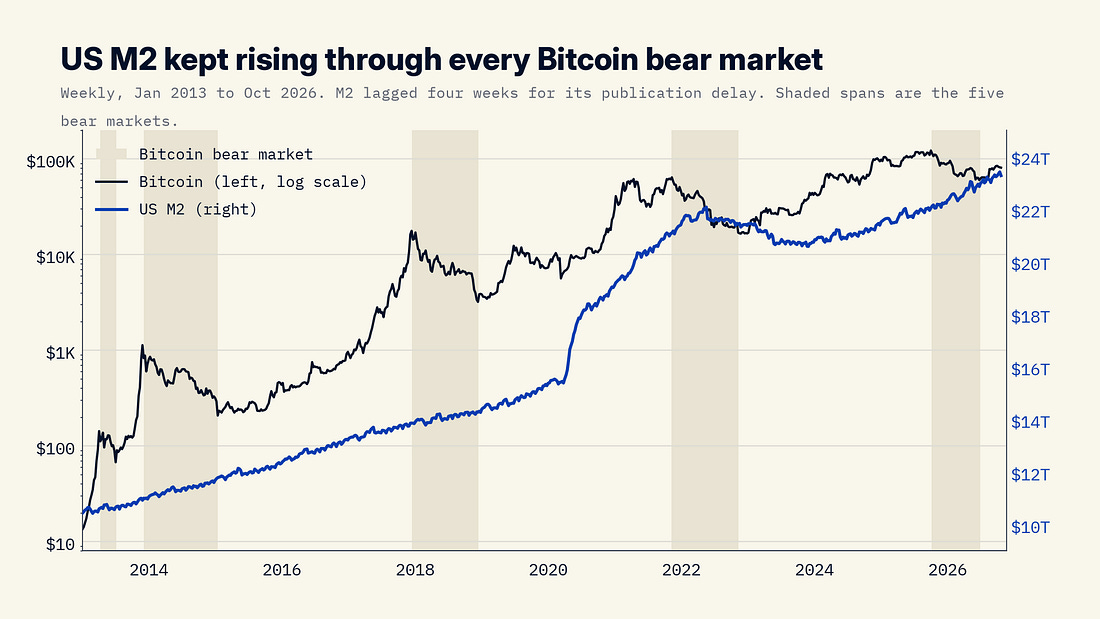
Across the weekly sample, the logarithm of Bitcoin’s price and US M2 correlate at 0.942. That sounds impressive until you notice that a straight line which does nothing but count the weeks correlates with Bitcoin at 0.946, and that M2 correlates with the same straight line at 0.971. Over this period M2 went from $10.4 trillion to $23.3 trillion and Bitcoin went from about $13 to about $80,000, so any two series that rose steadily over these years would line up this well. A formal test of whether the two levels share a long run relationship, rather than each drifting upward on its own, doesn’t find one. The test’s p-value is 8%, or 18% once a trend is allowed for.
The reason the overlay looks persuasive is that M2 almost never falls. On the seasonally adjusted monthly series (which I use for these descriptive figures because the raw weekly series dips every tax season) M2 rose in 88.5% of the 165 month to month changes in the sample and 71.5% on the unadjusted weekly series the tests use when read monthly. A line that rises nearly every month will look like it explains anything else that rises over the long run, and it will be silent about everything that falls. The bear markets show this plainly.
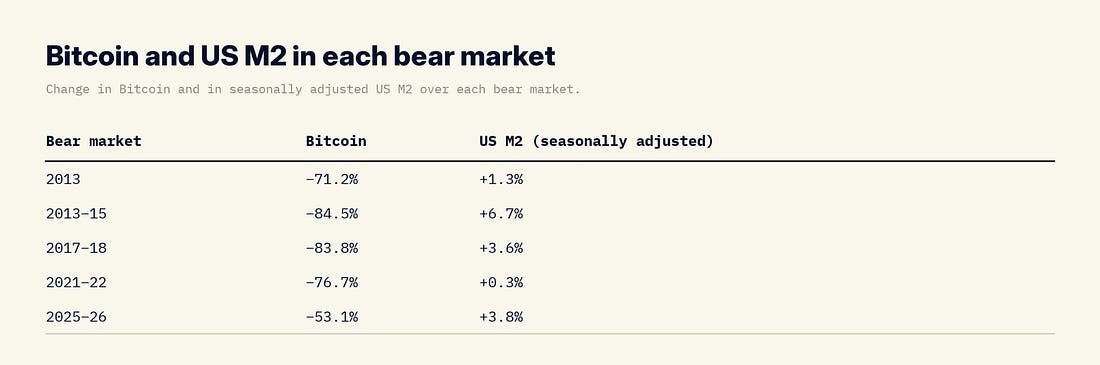
M2 grew through every one of the five bear markets while Bitcoin lost between 50% and 90% of its value. The bull markets don’t line up any better. M2 rose 48.2% during the 2018–21 bull, which included the pandemic stimulus, but it rose only 3.9% during the 2022–25 bull and 3.0% during the second 2013 bull, while Bitcoin multiplied many times over in each.
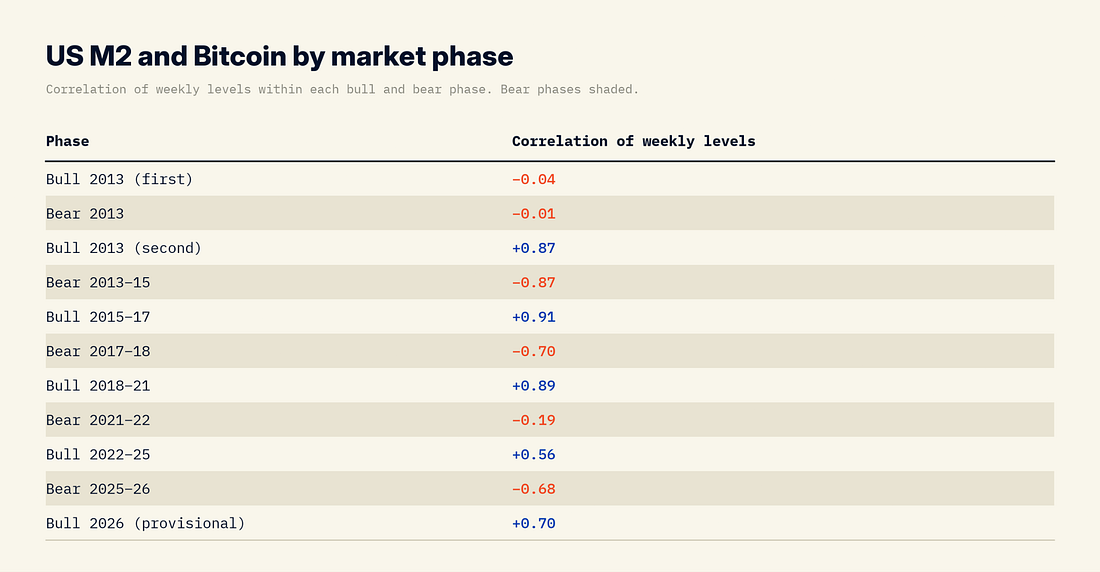
The within phase correlations tell the same story in a different way. If M2 were really driving Bitcoin, the two levels should move together inside each phase, and not only across the whole sample.
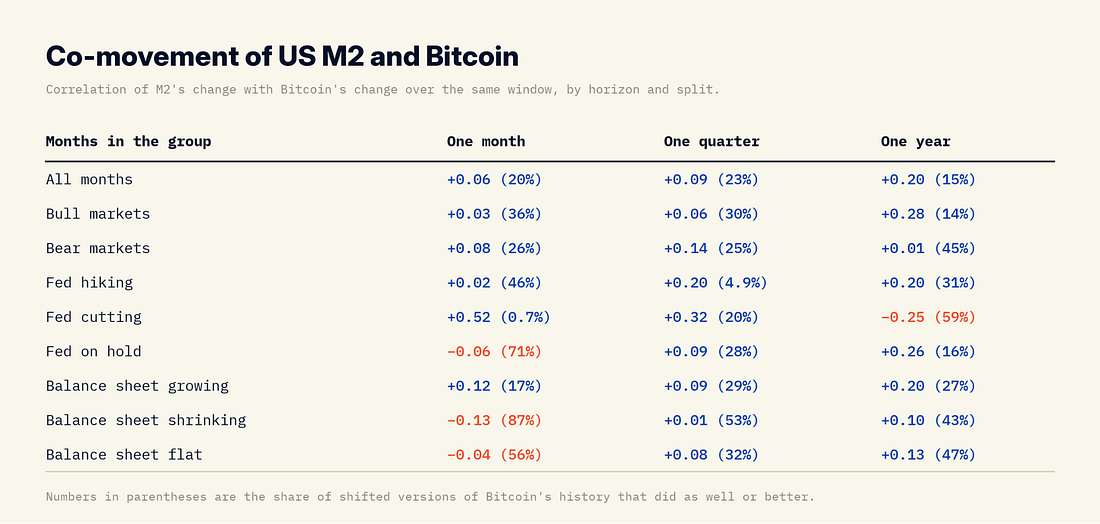
Inside bull markets the average is +0.65, inside bear markets it is −0.49, and pooled across everything it is +0.94, which is higher than any single phase. When the whole is greater than every one of its parts, the whole is mostly measuring the fact that both series went up over fourteen years. Inside bear markets the sign flips, because M2 keeps rising while Bitcoin falls. Apart from the first 2013 bear, which lasted only three months, the least negative bear is 2021–22. That is also the bear in which M2 barely grew, at +0.3%, and it led into the only real decline in M2 in the sample. M2 fell for nine straight months from August 2022 to April 2023, and by October 2023 it was 4.9% below its March 2022 peak. When M2 finally stopped rising, the chart came closest to working, which suggests the shared trend is doing most of the work. Co-movement The fair way to ask whether two rising series are connected is to compare their changes rather than their levels. Here are the correlations of M2’s change with Bitcoin’s change over the same window, by horizon and by split.
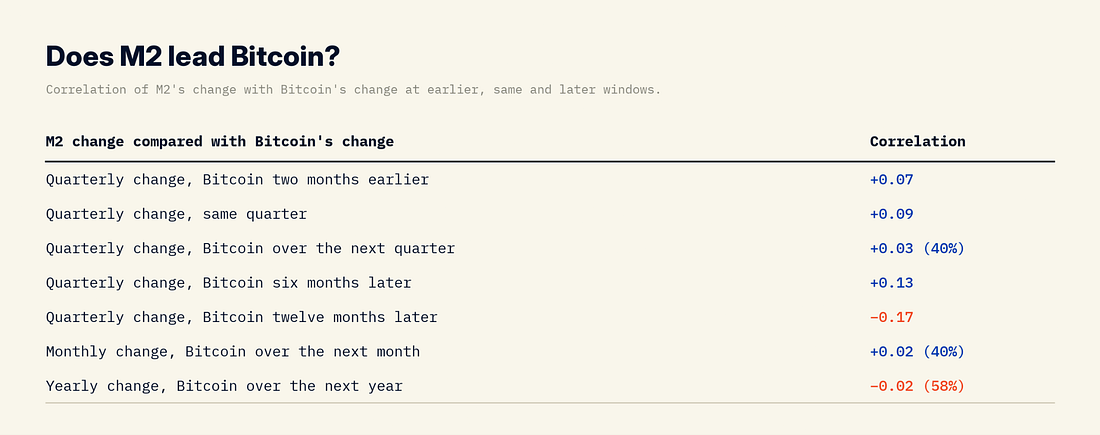
None of the full sample results clears chance at any horizon. The monthly and quarterly correlations are close to zero, and the yearly figure of +0.2 is something that one in seven shifted histories matches. The bull and bear rows look no better. Of the 32 split results for M2, two fall under 5%, and shifted histories produce at least two about 41% of the time, so that count is in line with chance. I looked hard at those two, because the cutting row in particular is large. In the 31 months when the Fed was cutting, monthly changes in M2 and Bitcoin correlate at +0.52, and the result holds at +0.53 over 27 months even after dropping the spring of 2020, which chance matches 1.4% of the time. It doesn’t carry over to longer horizons, though. Over a quarter it falls to +0.32, which chance matches a fifth of the time, and over a year it turns negative. M2 also didn’t move first in those months, which I come to next. The result also depends on how M2 is lined up with Bitcoin. Without the publication shift it is −0.06, with a two month shift it is +0.27 (12%), and on the seasonally adjusted series it is +0.16 (23%). It is the strongest single M2 result, so I treat it as something to watch, as I do the net liquidity lead results below, but with three cutting cycles and that sensitivity to timing I don’t count it as a finding. The hiking result over a quarter sits right at the 5% line and disappears at the other two horizons. Direction tells the same story. On the seasonally adjusted series, M2 and Bitcoin moved in the same direction in 52% of months, slightly below the 54% expected if the two were unrelated, given how often each rises. That splits into 62% of bull months, exactly what chance gives, and 29% of bear months, against 32%, and the reason is simple. M2 rises almost every month, so agreeing with it mostly means Bitcoin happened to rise too. I also reran the change correlations on the seasonally adjusted series, and none of them cleared chance there either (+0.03 monthly, +0.08 quarterly and +0.2 yearly). Lead The popular version of the claim goes further and says that M2 moves first. So the next question is whether M2’s change today lines up with Bitcoin’s change later.
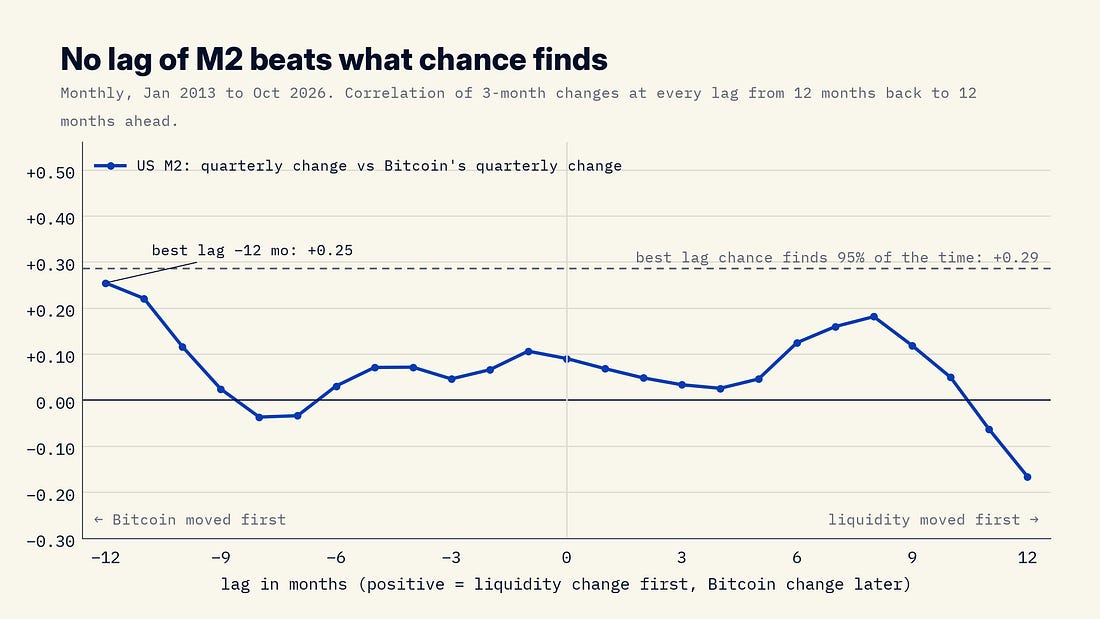
M2’s change this quarter tells us almost nothing about Bitcoin’s change next quarter, and the same holds a month ahead and a year ahead. To be charitable, I also searched every lag from twelve months back to twelve months forward and kept the best one, then compared it with the best lag that chance finds when Bitcoin’s history is shifted.
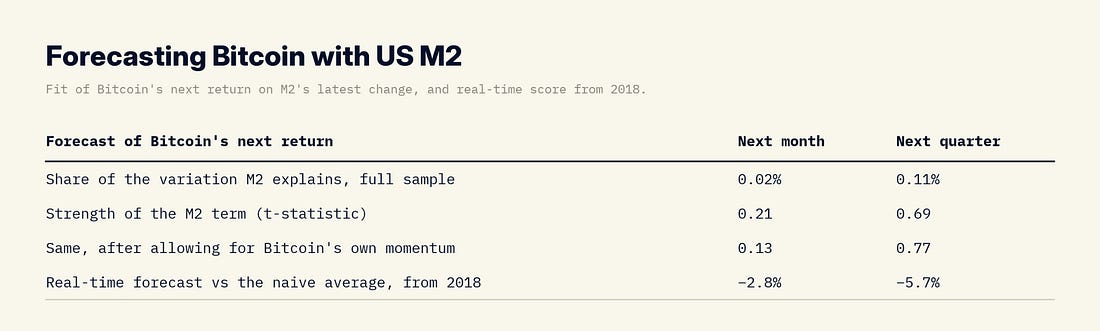
The best quarterly lag is twelve months in the wrong direction, with Bitcoin moving first, at +0.25. Chance finds a best lag at least that good a third of the time. If I only allow M2 to lead, the best is eight months at +0.18, against a chance level of +0.29. The best lag also wanders from cycle to cycle. It was twelve months in the wrong direction in 2013–15, M2 leading by eight months in 2015–18, by seven months in 2019–22, and twelve months in the wrong direction again in 2022–26. A real lead would sit in roughly the same place each time. Splitting the next quarter test by bull, bear, rates and balance sheet doesn’t find a lead either, as none of the eight groups clears chance. Even the cutting months, where M2 and Bitcoin moved together, show only +0.27 for the next quarter, which chance matches 22% of the time. Forecast If M2 leads at all, adding it to a forecast should help. I fit a simple model of Bitcoin’s next return on M2’s latest change, refit it each month using only the data available at the time, and scored it from 2018 against a forecast that just uses the average return so far.
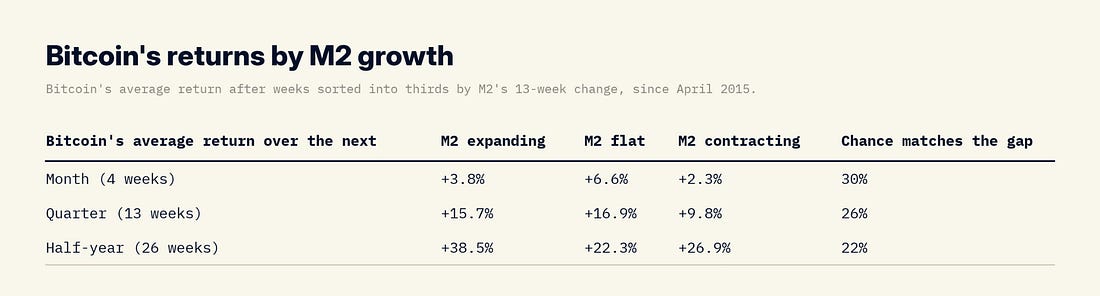
Even with hindsight, M2 explains essentially none of the variation in Bitcoin’s next return, and in real time it makes the forecast worse than simply assuming Bitcoin will do what it has done on average. The negative score means the naive average beat it. I ran the same scoring inside each split, and the only positive result was a 2.3% improvement over the next quarter in months when the balance sheet was flat, based on six scored months. Backdrop The last test is the most modest one. Even without a lead, Bitcoin might do better on average when M2 is growing quickly than when it is growing slowly. I sorted every week since April 2015 into thirds by M2’s 13 week change, using only the cutoffs known at the time, and looked at Bitcoin’s return over the following month, quarter and half year. One thing to keep in mind is that M2’s weakest third is mostly slower growth rather than decline. In the October 21 test week, the bottom third begins below +0.92% a quarter and the top third above +1.67%.
The ordering is not consistent across horizons, and none of the gaps between the top and bottom third clears chance. The splits make it worse for the M2 case. Inside bear markets, weeks when M2 was growing fastest were followed by a −42.9% average over the next half year, compared with −16.8% when it was growing slowest. Inside bull markets the thirds look much the same, with +6.5% against +7.2% over the next month and +21.2% against +24.6% over the next quarter. A simple rule that held Bitcoin only when M2’s 13 week growth was positive roughly matched holding it throughout, at +384% against +376% in weekly data from 2018 before costs, and chance does as well on a risk adjusted basis 35% of the time. The same rule on yoy growth returned +24%. Why the M2 case fails Put together, US M2 doesn’t meet any of the four conditions in Section 2. Its changes don’t move with Bitcoin’s beyond what chance produces, it doesn’t move first at any horizon or lag, it doesn’t improve a forecast made in real time, and Bitcoin’s returns don’t sort by it in a way that clears chance. The tight fit on the chart comes from two series that both rose over the same fourteen years, and it reverses inside every bear market, because M2 kept growing while Bitcoin fell. That isn’t surprising given what M2 is. A broad stock of deposits that rises with the size of the economy is a poor gauge of the money that is free to bid on anything at the margin, and the results above are consistent with that. 6. Net Liquidity Examined Now that the flaws with M2 have been established, let’s see how Net liquidity stacks up against the same tests with the same time frames. As a reminder, here is what I mean exactly by “net liquidity”: Net liquidity = Fed total assets − Treasury General Account − overnight reverse repo.
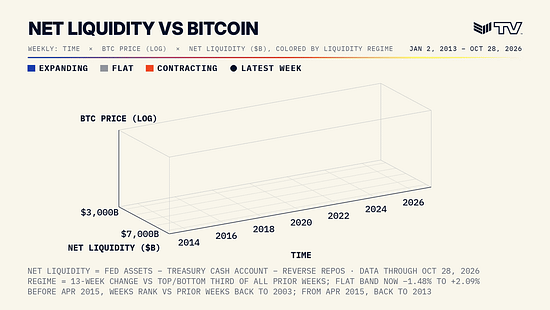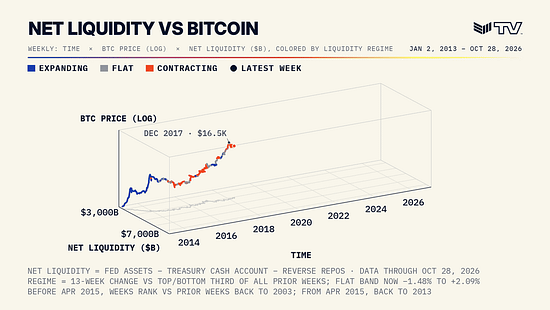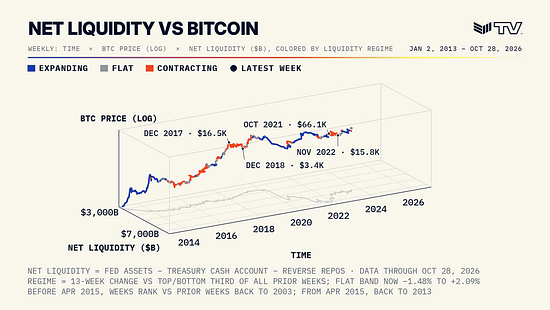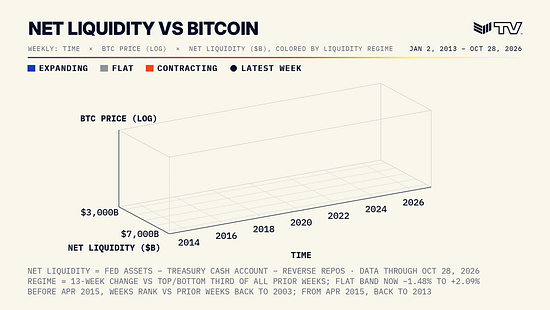
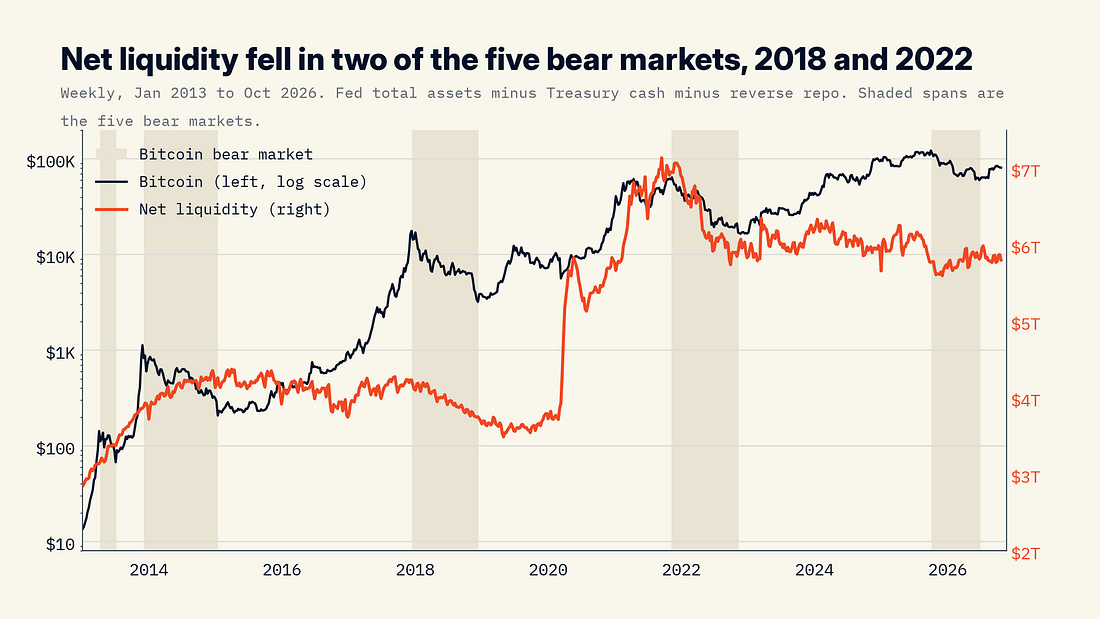
The levels On levels, net liquidity fits Bitcoin’s chart worse than M2 does. The correlation with log Bitcoin is 0.81, against 0.946 for the straight line that counts weeks, and net liquidity itself correlates with that line at only 0.815. It went from $2.85 trillion to $5.8 trillion over the sample, but not in a straight line, and the formal test for a long run relationship in levels doesn’t find one. The test’s p-value is 54%, or 29% with a trend. I think that weaker fit could be a point in its favor, because a measure that doesn’t simply trend up can’t borrow Bitcoin’s trend, so whatever relationship survives the next tests has to come from the series actually moving together.
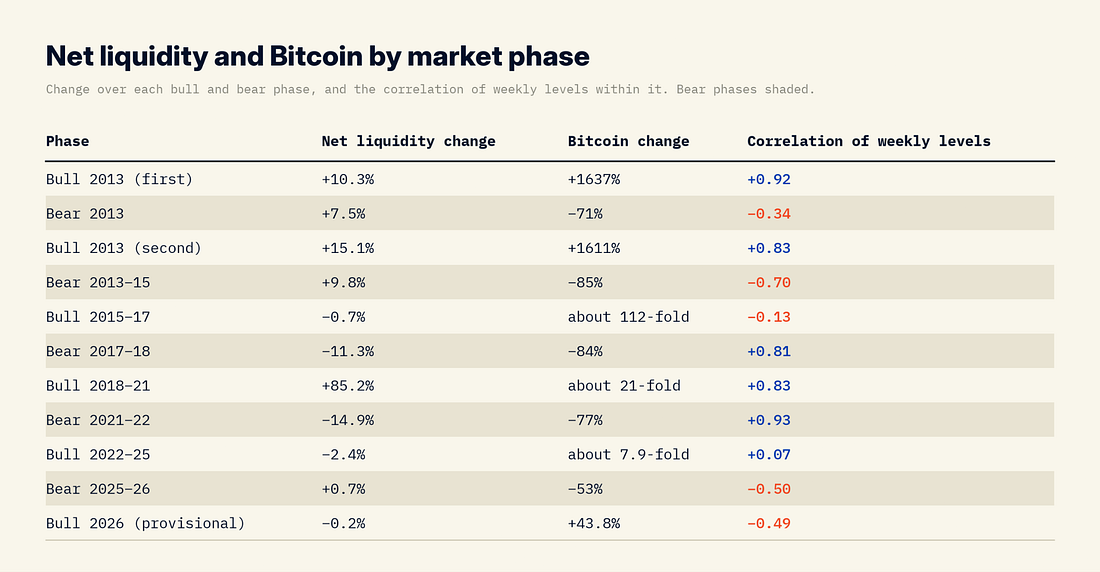
Two things stand out in this table. The first is that net liquidity fell in two of the five bear markets, 2017–18 and 2021–22, and those are the two bears where its level tracked Bitcoin closely, at +0.81 and +0.93. The second is that two of the largest bull markets happened with no help from net liquidity at all. Net liquidity was slightly lower at the end of both the 2015–17 and 2022–25 bulls even as Bitcoin multiplied many times over, and only the 2018–21 bull came with a large rise. The pooled correlation of 0.81 is also lower than four of the individual phases, the opposite of what happened with M2, so the whole is not borrowing strength from a shared trend.
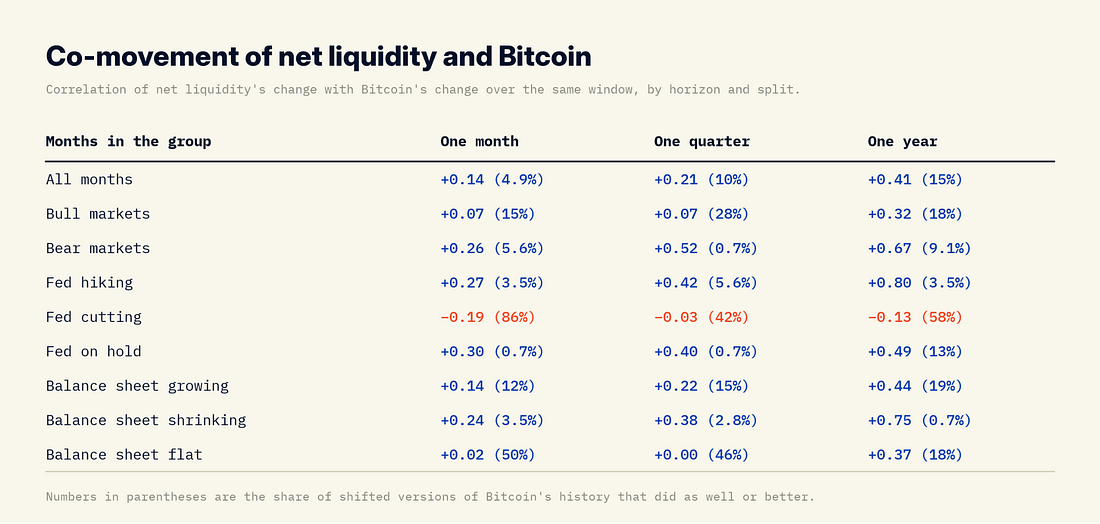
Co-movement On changes, net liquidity does better than M2.
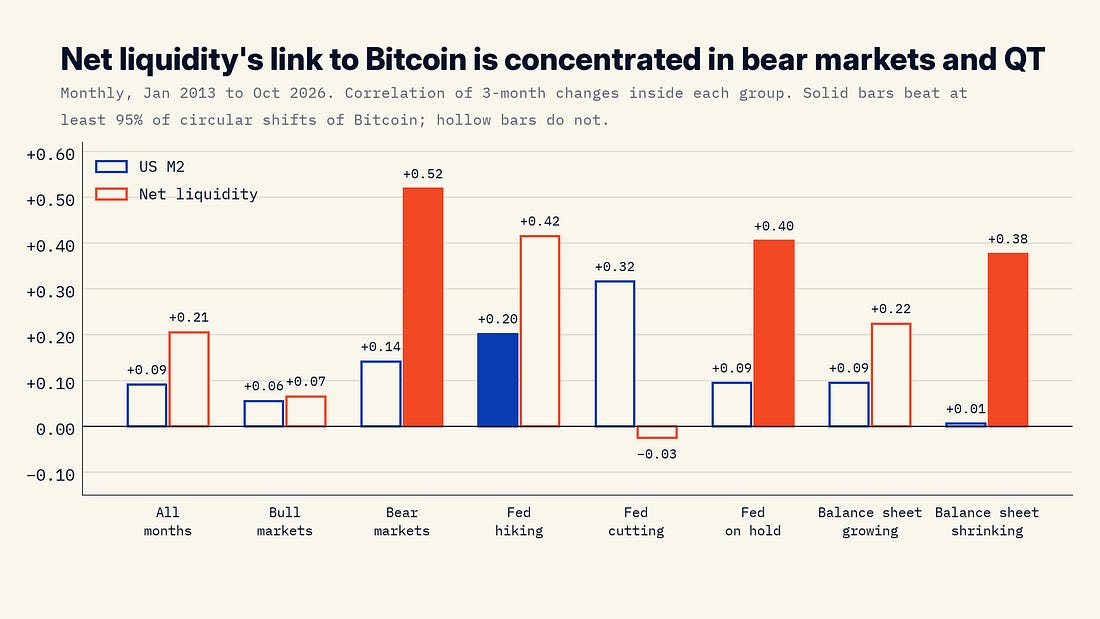
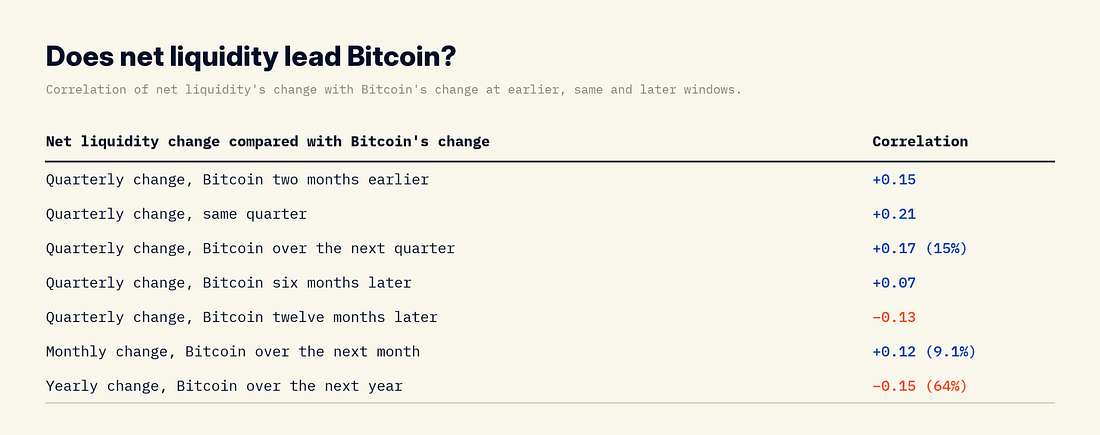
Across all months, the correlation of changes is roughly double M2’s at every horizon. The monthly figure just clears chance, while the quarterly and yearly figures are larger but don’t, partly because a fourteen year sample only holds a handful of independent years, and chance matches the yearly one about as often as it matches M2’s (15% for both). Direction agreement is 62% of months, against about 51% expected if the two were unrelated, and unlike M2 it holds up in both kinds of market, at 60% of bull months and 65% of bear months against 54% and 51% by chance. The splits show where the relationship is concentrated. Ten of the 32 split results clear chance, eight in this table and two in the lead tests below. None of the 142 shifted histories produced as many as ten, so chance matches that count less than 1% of the time, and the ten cluster in a clear way. In bear markets the quarterly correlation is +0.52, while in bull markets it is +0.07. The correlations are relatively stronger when the Fed was hiking, on hold or shrinking its balance sheet, and they disappear in cutting months. Net liquidity has tracked Bitcoin most closely in bear markets, which could be coincidence or due to Bitcoin tending to have been the first asset of choice amongst investors in need of a trim throughout its lifespan (my speculation). Part of this edge comes from timing, since net liquidity’s data reaches us more quickly. If I give net liquidity the same four week shift, its monthly correlation falls to +0.09, which chance matches 10.5% of the time, and six of its 32 split results clear chance, against two for M2, a count shifted histories reach about 9% of the time. If I shift neither series, M2’s quarterly correlation is +0.12 against net liquidity’s +0.21, and one of M2’s split results clears chance against ten for net liquidity.
I checked whether a couple of episodes were carrying this. Dropping the spring of 2020 makes the full sample monthly correlation stronger, at +0.23, which chance matches less than 1% of the time. Dropping the 2017–18 and 2021–22 bears, the two in which net liquidity fell, leaves the remaining bear months at +0.53 over a quarter, though on only 25 months it no longer quite clears chance (5.6%). Counting the 2021 correction as a bear barely changes anything, with bear months at +0.49 over a quarter (3.5%) and bull months at +0.06. The bear market pattern isn’t just two episodes, though with five bears in the sample it can’t be called settled either. In the weekly data, dropping 2022–23 weakens the four week correlation from +0.14, which already sits just inside what chance produces, to +0.10, and the rolling two year correlation cleared chance in only 110 of 614 windows, 104 of them ending between May 2022 and June 2024. Lead On this test net liquidity fails the popular claim, as M2 did.
The strongest link at every horizon is in the same window, with no lag at all. Net liquidity’s change this quarter correlates +0.17 with Bitcoin’s change next quarter, which is better than anything M2 managed, but chance matches it 15% of the time. The next month looks a little better at +0.12, and still doesn’t clear chance.
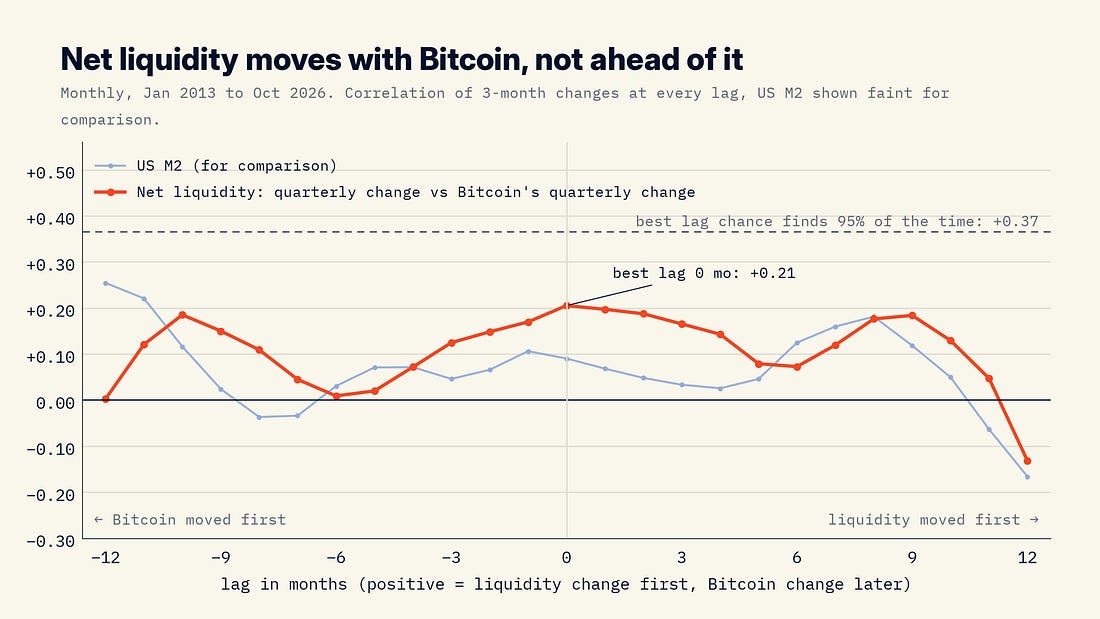
The lag search confirms it. The best lag is zero at the monthly, quarterly and yearly horizons, so the two series move together rather than one after the other. The lags just either side of zero look nearly as good because overlapping quarters share months, so they mostly echo the same time link. The best quarterly correlation of +0.21 is well under the +0.37 that chance finds as the best of all lags, and chance beats it about two thirds of the time. Cycle by cycle, the best lag moved from seven months in the wrong direction in 2013–15 to net liquidity leading by four months in 2015–18, nine months in 2019–22 and two months in 2022–26, which isn’t a stable lead. There are two exceptions worth reporting. In the months when the Fed was hiking, net liquidity’s change this quarter correlated +0.48 with Bitcoin’s change next quarter, which chance matches 2.8% of the time over 58 months. In the months when the balance sheet was flat, the same figure was +0.38, which chance matches 4.9% of the time over 40 months. While the balance sheet was shrinking it was +0.25, which doesn’t clear chance. The hiking result fits the co-movement pattern above, while the flat result sits right at the 5% line and has no counterpart in the co-movement table. These are two cells out of eight, and a careful reader should treat them as something to watch rather than a finding. Forecast
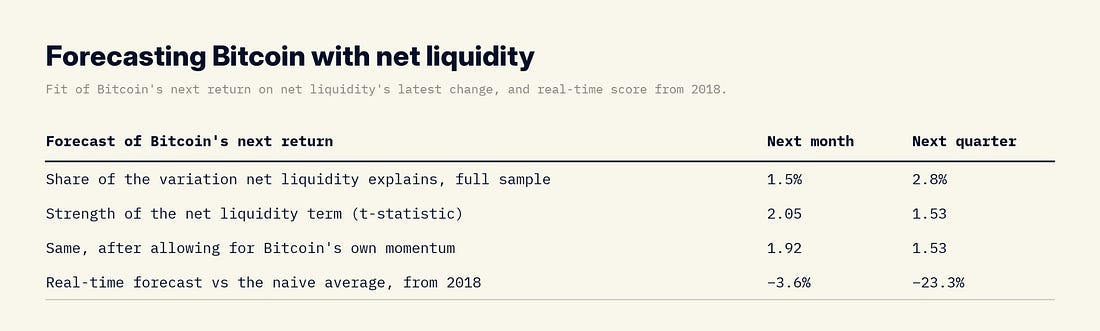
With hindsight, net liquidity explains more than M2 does, and the monthly term is borderline significant. In real time it still loses to the naive average at both horizons, badly over a quarter, and by more than M2 does at both. Over the next quarter, the real time forecast beat the naive average by 9.6% in hiking months, 9.9% while the balance sheet was shrinking, 27.3% in bear markets and 13.9% in the six scored months with a flat balance sheet. It lost by 60% in bull markets, 236% in cutting months and 62% while the balance sheet was growing, and over the next month none of the rate or balance sheet groups helped. Still, picking the groups that worked after the fact is hindsight, and my earlier work found the Fed’s decisions haven’t reliably sorted Bitcoin’s returns either way. Backdrop
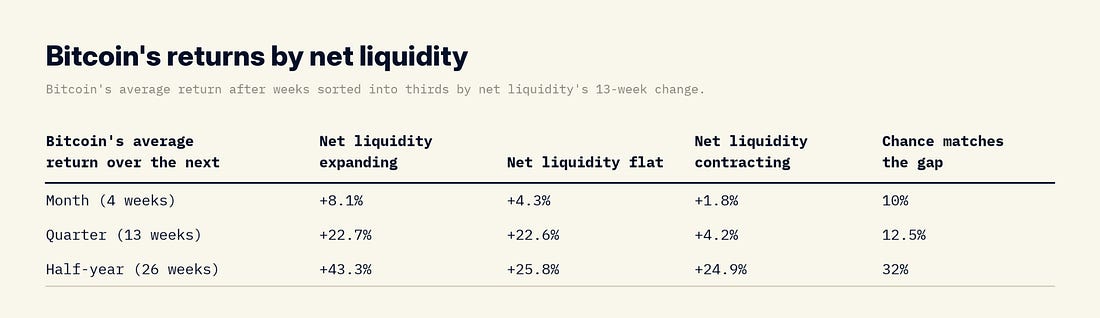
These thirds have a direct reading, since in the October 21 test week the bottom third is a 13 week decline of more than 1.44% and the top third is a rise of more than 2.09%. The ordering runs the way the liquidity view predicts at every horizon. Over the next month Bitcoin averaged +8.1% after expanding weeks, rising in 62% of them, and +1.8% after contracting weeks, rising in 54%. Over the next quarter the gap is +22.7% against +4.2%, and the flat third rose most often, in 69% of weeks against 65% after expanding weeks and 52% after contracting ones. For comparison, the average across all weeks was +4.0% over a month, +13.6% over a quarter and +29.1% over a half year. None of the gaps clears chance, though the monthly and quarterly ones come closer than anything M2 produced, and contracting liquidity has come with weaker returns rather than crashes. The bull and bear split shows where the gap comes from. Inside bull markets, Bitcoin did about as well after contracting weeks as after expanding ones, at +7.8% against +9.2% over the next month and +22.5% against +25.4% over the next quarter, and over the next half year it actually did better after contracting weeks, at +68.8% against +44.6%. Inside bear markets, 101 weeks fell in the contracting third and only 9 in the expanding third, and over the next half year Bitcoin averaged +14% after the five expanding weeks counted at that horizon, against −26.5% after the 101 contracting ones. Most of the backdrop gap comes from bear markets that happened while liquidity was draining. In weekly data from 2018 before costs, a rule that held Bitcoin only when net liquidity’s 13 week change was positive returned +272% against +376% for holding throughout, though with a better risk adjusted return that chance matches 24% of the time, while a rule that stepped aside only in the contracting third returned +516%, and chance does as well on a risk adjusted basis 15% of the time. Where net liquidity holds up and where it fails Net liquidity does better than M2 on the co-movement, direction and backdrop tests, though not in real time forecasting, where it loses to the naive average by more than M2 does (−3.6% against −2.8% over a month and −23.3% against −5.7% over a quarter). Its changes move with Bitcoin’s beyond chance at the monthly horizon, it agrees on direction in bull and bear markets alike, and the relationship has been strongest in bear markets and while the Fed was hiking, on hold or shrinking its balance sheet. The drains weren’t always the Fed’s doing, though. In the 2021–22 bear, net liquidity fell about a trillion dollars while the Fed’s assets barely moved, and in the 2022–25 bull market the Fed ran off roughly $2 trillion while net liquidity hardly changed. It fails on the part of the claim that people actually want. It doesn’t move first by a stable lag, it doesn’t beat a naive forecast in real time, and in bull markets it tells us almost nothing, since the largest bull market in the sample and the most recent one both happened while net liquidity went sideways. Net liquidity describes the conditions Bitcoin is trading in, but it hasn’t told us what Bitcoin will do next or how large a rally will be. 7. Conclusion Of course, there are limits to all of this. Fourteen years of Bitcoin history holds only five bear markets and even fewer liquidity cycles, so every split result rests on a small number of episodes, and a single cell that clears chance may be luck. Also, all of these are correlations, which as everyone knows is not indicative of causation. Net liquidity moving with Bitcoin during a drain is consistent with the liquidity mechanism, but it is also consistent with both responding to the same external forces, and these data points can’t separate the two. Yet, of course, my aim in doing this was never to prove any sorts of claims of causality, nor to prove any claims at all for that matter, but simply to put claims of M2 and Bitcoin correlation to the test. Net liquidity does better than M2 in most of the same tests. It moves with Bitcoin in the same windows, especially in bear markets, and Bitcoin’s returns have been weaker on average while it contracts, though none of those gaps clears chance. Yet, it still doesn’t lead Bitcoin by any lag that beats chance, and its real time forecasts did worse than M2’s. When liquidity has been draining the market has had less room for error, but added liquidity has said little about how far a rally goes. So, I’d use net liquidity, amongst other data points, to describe the broader environment and not as a tool for trading.
Special thanks to our sponsors: Cash App, Square, Bitkey, Stand with Crypto, PLAUD, VerifiedX, SALT, and UTXO Check back here on Monday for the next Substack post with the full schedule for next week’s guest speaker lineup. For daily updates, follow us on X. For full show recordings and clips, subscribe to our YouTube channel. And for everything BMTV, visit watchbmtv.com. Thanks for tuning in. Until next time! The BMTV Team Disclaimer: This newsletter is for informational purposes only and should not be considered financial advice. Always do your own research before making any investment decisions. We sincerely appreciate your support and hope you found this content valuable. Please leave a like and let us know your thoughts in the comments section; we always welcome feedback from our audience!
|